

Planning a staff Christmas party around £150 per person?
HMRC’s annual functions exemption can help an employer plan a celebration, but the figure is a limit on the whole qualifying event, not a £150 drinks allowance. A considered cocktail bar can still fit into that budget. The useful question is what remains for every part of the party once drinks, food, venue and logistics are counted together.
What the rule actually covers
HMRC says an annual party or similar function can be exempt from employee benefit reporting and tax if it is open to all employees and costs no more than £150 per person. Businesses with separate locations or departments can hold appropriate separate events under HMRC’s conditions. Multiple annual events may qualify only where their combined cost per person stays within the limit.
The £150 is an exemption, not an allowance. If an event does not qualify because its cost is over the limit, the full cost of that event is potentially reportable, rather than just the amount above £150. Employers should check their own circumstances with their finance or tax adviser.
Work out the cost using the entire event bill, including VAT and any transport or overnight accommodation provided to enable attendance. HMRC calculates cost per head by dividing that total by everyone who actually attends, including guests who are not employees. Catering, venue, entertainment and drinks belong in the same calculation. A client reception or a one-off promotional event should not be assumed to qualify as an annual staff function.
What could a Twist Christmas bar cost within that plan?
Here is a simple illustration for 100 attendees, assuming one eligible annual party and no other annual function using the exemption. At £150 per attendee, the full-event ceiling would be £15,000 including VAT. The figures below use our published guide prices for 100 guests and 20% VAT. They are bar components of an overall event budget, not a statement that the entire party qualifies.
Festive cocktail reception, up to two hours — from £25 per person + VAT; £30 including VAT. For 100 guests, that is £3,000 including VAT. It includes three cocktails or alcohol-free alternatives per guest, with bartenders, standard mobile bar, glassware, ice, ingredients, standard setup and pack-down. In the £15,000 illustration, £12,000 remains for everything else before separately quoted transport and venue logistics.
Festive cocktail reception, up to three hours — from £30 per person + VAT; £36 including VAT. For 100 guests, £3,600 including VAT, leaving £11,400 in the same illustrative whole-event envelope before transport, venue and other costs.
Christmas party bar, up to four hours — from £45 per person + VAT; £54 including VAT. For 100 guests, £5,400 including VAT, leaving £9,600 for the rest of the illustrated event. This package includes five drinks per guest, including cocktails; the remaining drinks can be house sparkling wine, beer, wine or soft drinks. It includes the standard bar service and equipment.
An optional sparkling welcome is from £6 per person + VAT, or £7.20 including VAT, for one extra 125 ml glass of house sparkling. For 100 guests that adds £720 including VAT to the event total.
These are starting prices, not final quotes. Menus and bars can be customised and branded, with additional work quoted for the brief. We provide tailored quotes for 50–99 guests. Transport and venue logistics are quoted separately, based on location, access, loading, parking and collection. Request a written quote and add every supplier’s VAT-inclusive cost before applying the HMRC test. A lower bar cost may create more room for excellent food or a distinctive venue; using an existing office or venue may also change the overall economics, depending on the brief.
A winter cocktail worth making space for
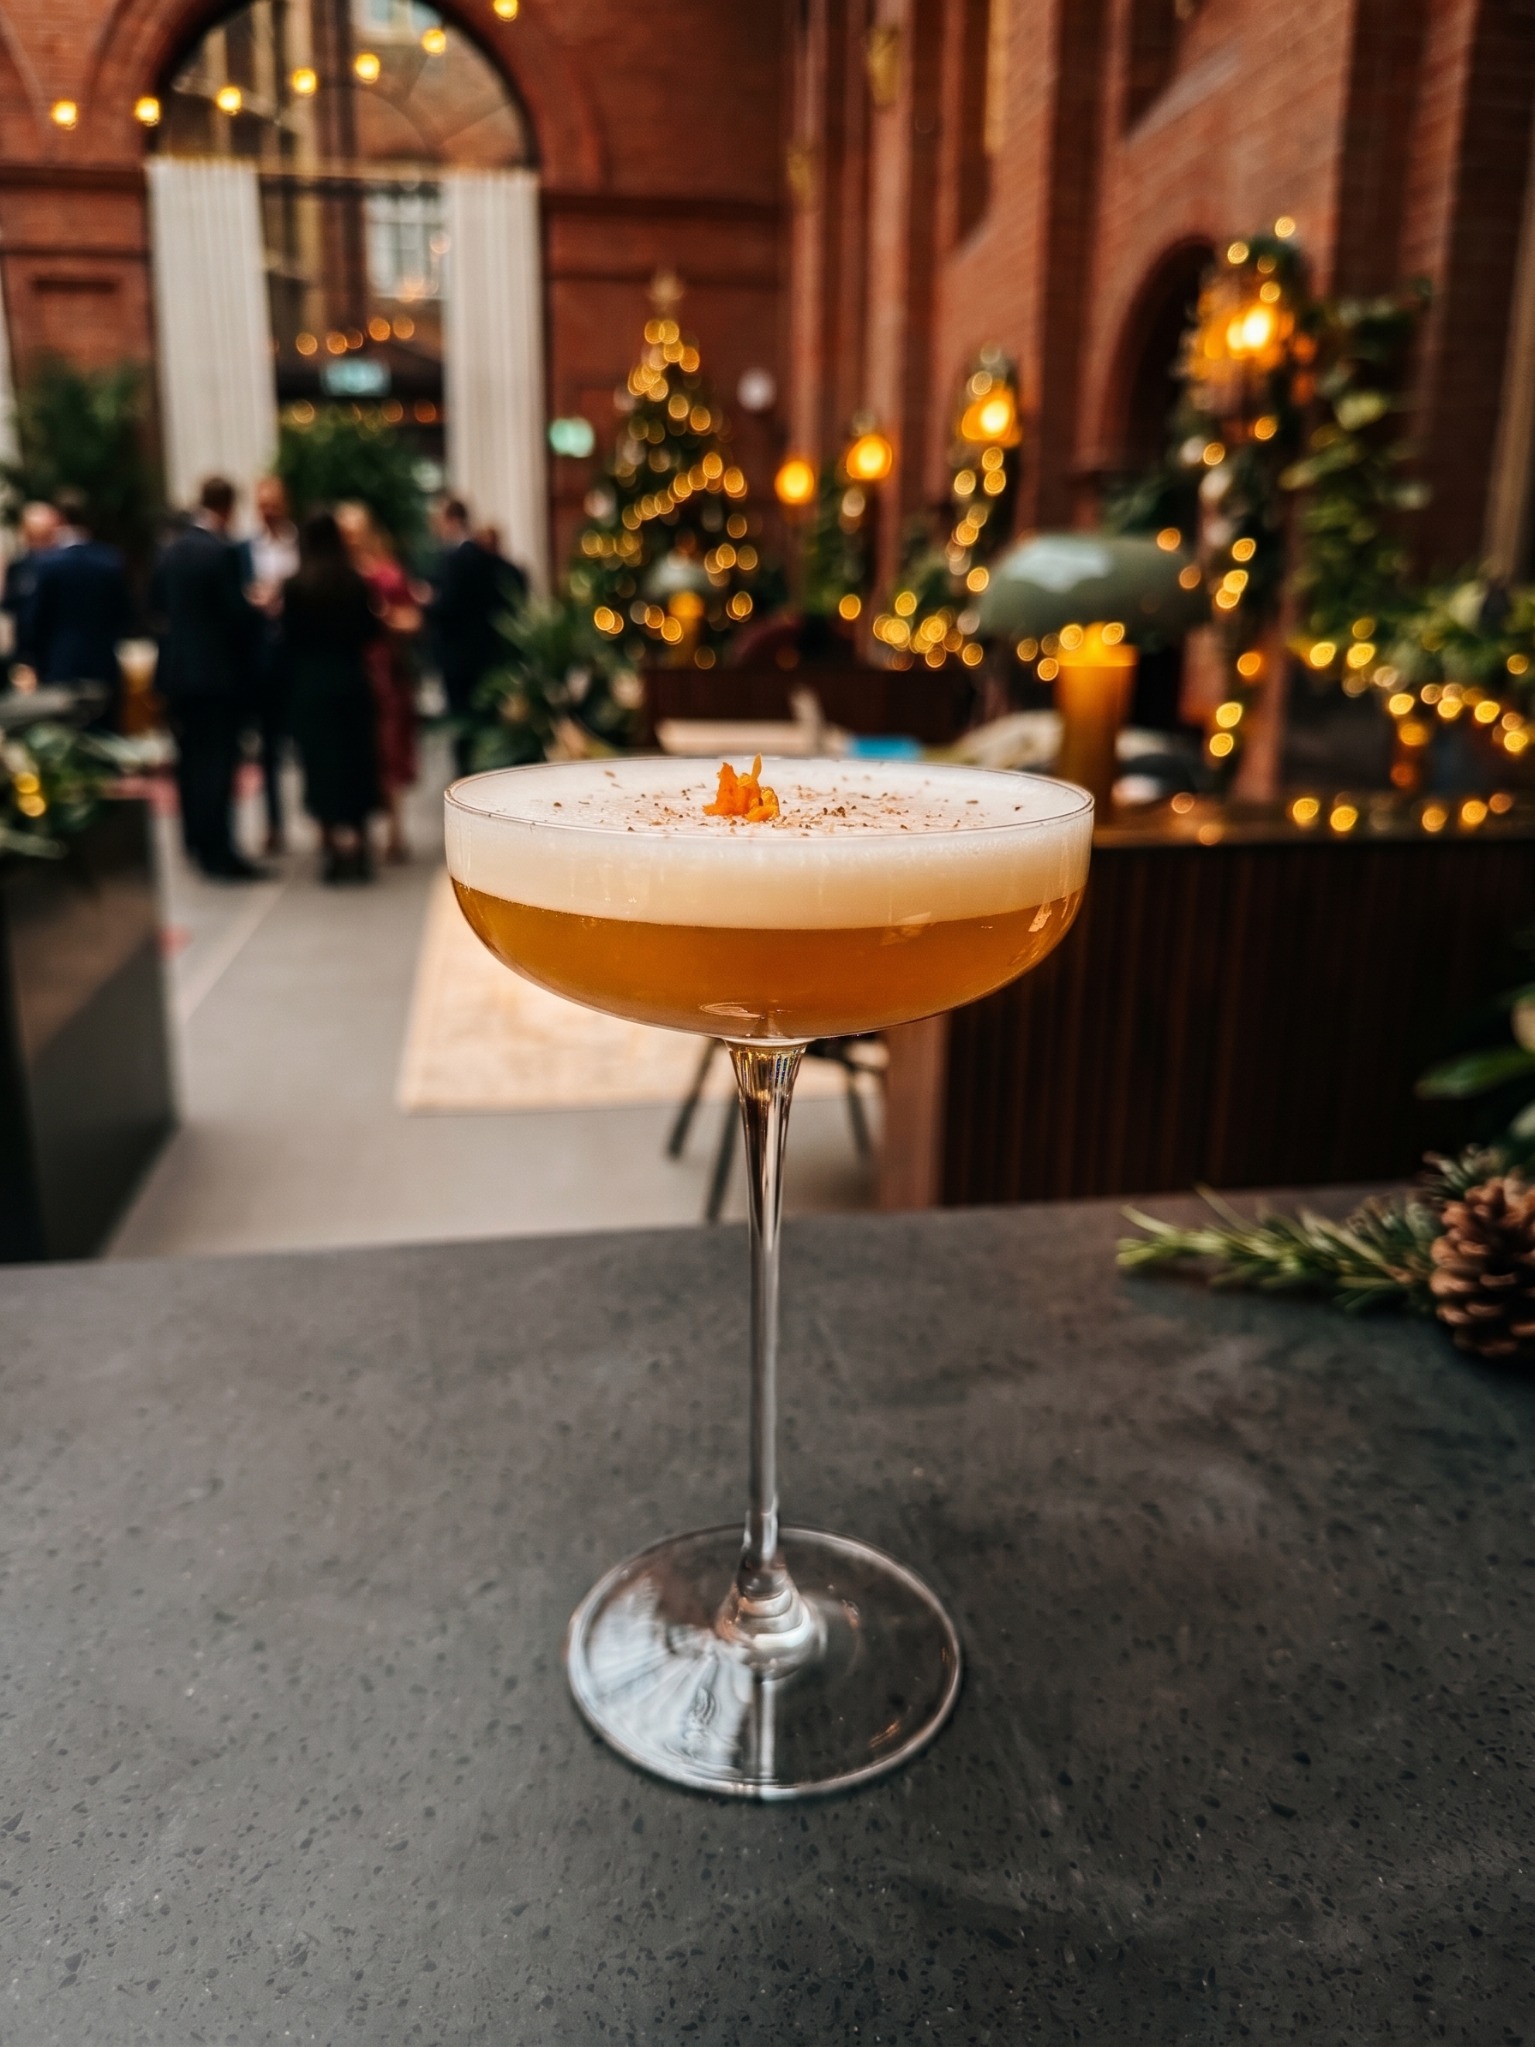
Our Alpine Sour brings bourbon, homemade Douglas fir syrup, lemon juice and a dash of bitters together in a winter take on the whisky sour. Its citrus and evergreen notes feel right for a Christmas gathering, served in a coupe with a considered garnish. We develop bespoke menus around each event, including thoughtful alcohol-free options; this is a seasonal idea, not a fixed list guests must choose from.
A short planning checklist
1. Confirm the event is an annual staff function and who is eligible to attend.
2. Check whether other annual functions in the same tax year use part of the £150 limit.
3. Budget the actual attendee count and the complete VAT-inclusive event cost, including transport or accommodation provided.
4. Choose the bar format and service length to suit the event, then ask for a written quote that includes logistics.
5. Leave some headroom for changes in guest numbers or supplier costs, and have your finance adviser confirm the treatment.
Planning a London Christmas party? Tell us the date, venue, guest count and the feel you want. We can suggest a cocktail experience and send a tailored quote within one day: Explore Christmas packages and request a quote
Sources and further details
Twist Christmas packages: View Twist Christmas packages
HMRC annual party exemption: Read HMRC’s annual party exemption overview
HMRC reporting when an event does not qualify: Read HMRC’s reporting guidance
HMRC detailed cost calculation: Read HMRC’s cost calculation guidance
Discover Related Blog Posts


Subscribe to The Plot Twist
Real-life stories of close calls, crises averted and calamities pacified in this one-of-a-kind newsletter. Learn how to steady a storm, while sitting on the edge of your seat.